
MSP Vendor Consolidation: Why the Math Isn’t Mathing
Estimated Reading Time 3 min read
er MSP Vendor Consolidation: Why the Math Isn’t Mathing
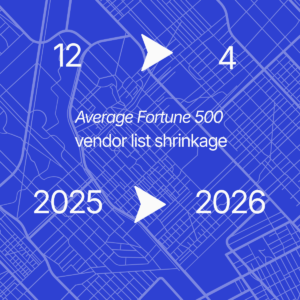
MSPs just cut their vendor list from 12 to 4. They’re calling it “simplification.” Cute story. Let’s check the math — because it isn’t mathing. 🧮
MSP vendor consolidation sounds tidy in a boardroom deck.
Fewer vendors.
Lesser number of invoices.
Shorter awkward vendor calls.
However, fewer names on the official roster does not equal less work being outsourced. It just means the work is sliding sideways, into overflow and subcontract channels that never show up on the pretty org chart.
The Numbers Behind the Consolidation Story
A few data points are worth sitting with before anyone calls this simplification a win.
SHRM pegs the 2025 median time-to-fill at 44 days. Specialized roles routinely blow past that number. Meanwhile, only 41% of employers say they track contingent workforce spend in real detail. The rest are essentially flying on vibes and a quarterly PowerPoint.
On top of that, the US contingent workforce market has already crossed $200 billion in managed spend. It’s still climbing, even as primary vendor lists keep shrinking. So the pie isn’t getting smaller. It’s just getting served to fewer people at the table.
The Paradox Nobody Puts on a Slide
Here’s the part that rarely makes it into the QBR deck: MSPs are downsizing the front door while quietly building a much bigger back door.
The primary list gets a glow-up. Three, maybe four “strategic partners.” Logos on the deck. Quarterly business reviews with actual sandwiches. Meanwhile, the overflow and subcontract bench is doing far more heavy lifting than ever, filling the reqs the primary vendors can’t touch — minus the visibility, minus the pricing power, and definitely minus the sandwiches.
In short, it’s consolidation on paper. It’s expansion in practice. Same spend, fewer names, more plausible deniability.
Fewer Vendors on Paper, Same Circus
For anyone managing this shift day to day, the punchline writes itself. Consolidation was supposed to simplify the program. Instead, the same complexity just found a new person to juggle it.
Therefore, the suppliers absorbing that complexity deserve a closer look. Increasingly, they’re doing tier-1 work on tier-3 terms, with zero seat at the table where the real decisions get made. Nobody warned them the org chart was a magic trick.
More Work, Less Table
That tension is really the whole story in five words: more work, less table.
Meanwhile, on the other side of the same coin, it’s less list, same spend.
Consequently, this isn’t really a story about fewer vendors. It’s a story about where accountability quietly moves once a list gets shorter.
The Real Question Behind MSP Vendor Consolidation
So here’s what’s genuinely worth asking, from both sides of the table.
- If you’re a subcontract or overflow supplier: has your actual workload gone up even as your official standing with the MSP has gone down?
- And if you sit on the program or MSP side: is reducing vendor count really reducing complexity — or is it just relocating that complexity somewhere nobody has to report on?
Ultimately, the gap between the org chart and the org reality is worth talking about honestly, rather than papering over it with a shorter vendor list and a tidier slide.
++++++++++++++++++++++++++++++++++++++++++++++++++++++++++++++++++++++++